Vaste Amasserance continuously analyzes market flows and transforms statistical noise into actionable signals, with daily reporting that documents each recommendation.
Our machine learning models process volumes of market data beyond what a trader can track manually: order books, volumes, inter-asset correlations and volatility history. Each signal generated is accompanied by its confidence level and its underlying assumptions.
The objective is not to replace your judgment, but to feed it with structured and verifiable information, tested beforehand in historical conditions via backtesting.
Simplified visualization intended to illustrate the structure of the actual dashboard.
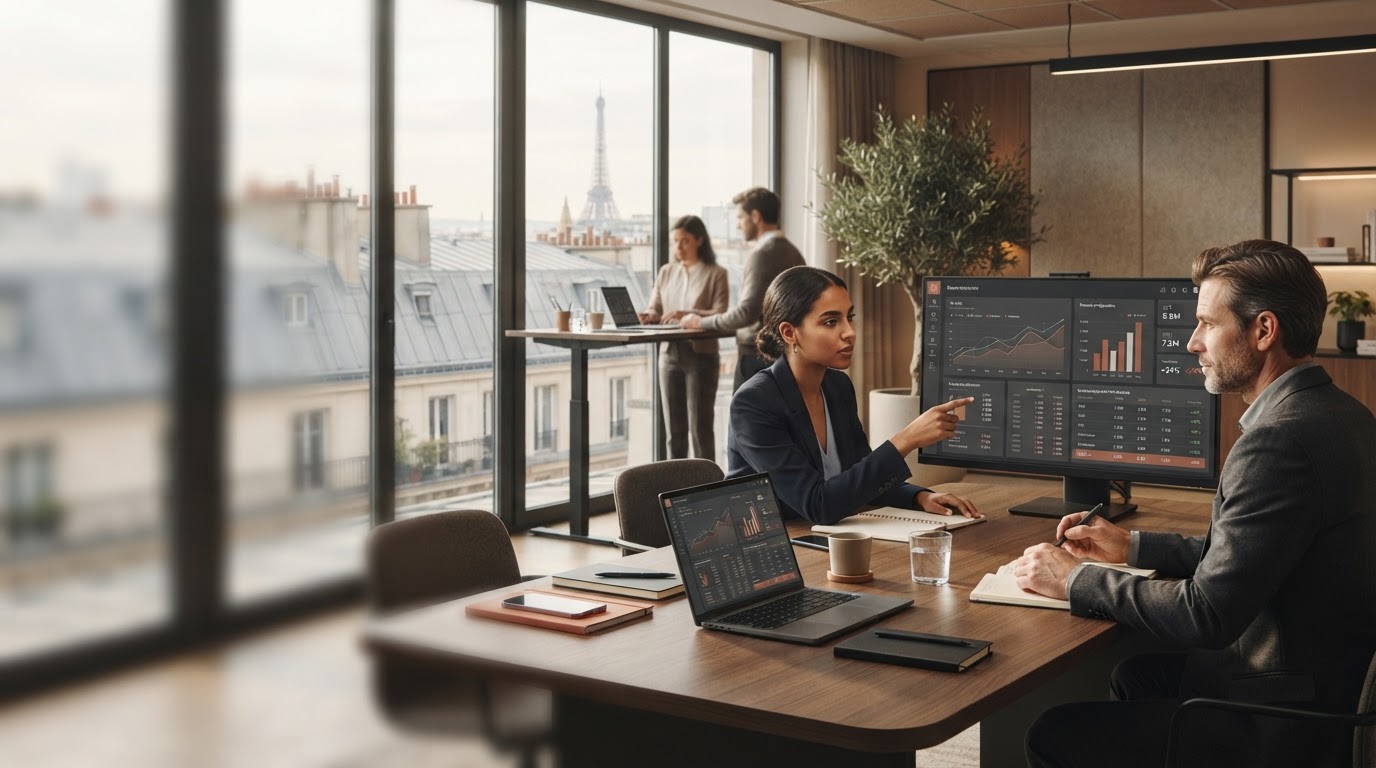
Each market session results in a report detailing the signals issued, the suggested positions and their actual outcome, including when performance is negative. The gap between forecast and execution — including slippage — is recorded for each operation.
The values shown are a formatting example and do not represent actual performance. The dashboard provided to each user provides data specific to their account.
Three components work together to produce usable recommendations without exposing the user to unsupervised automatic decisions.
Market feeds are ingested and processed continuously, with processing time measured in milliseconds to limit the gap between detection and notification.
Each recommendation is weighted by an exposure and volatility calculation, with alert thresholds configurable according to your risk tolerance.
The models are recalibrated based on actual results observed, and each version of the model remains comparable to the previous one via archived backtesting reports.
Vaste Amasserance was designed for traders who want to understand how a signal was produced, not just receive it. Each model update has a release note explaining what has changed and why.
The market data used comes from recognized third-party providers; no personal trading data is shared with external entities without explicit consent.
The integration is designed to adapt to existing configurations rather than to impose a change in the trading environment.
Connection to the market sources you already use, with verification of the consistency of the flows before putting them into production.
The parameters are adjusted according to your trading horizon and your usual instruments, then backtested over a representative period.
The first weeks of use are closely monitored in order to adjust the alert thresholds and the sensitivity of the risk engine.
Each signal is associated with a confidence score calculated from the performance of the model in backtesting and its consistency with current market conditions. This score is visible in the daily report, alongside the variables that influenced the recommendation.
Yes. No machine learning model guarantees a future outcome, and performance reports always include signals that have had an unfavorable outcome. Full history remains viewable, including periods of underperformance.
Market data and configuration settings are encrypted in transit and at rest. Access to dashboards is individual and no position data is shared between user accounts.
Slippage refers to the difference between the price anticipated by the model at the time of the signal and the price actually observed during execution. It is measured and displayed for each operation so that the user can evaluate the real accuracy of the system, beyond theory.
Yes. The system produces documented recommendations; the final execution remains a user decision, whether manually or via an automation rule that you define yourself.
Before any implementation, you can review a complete sample dashboard and daily report to assess whether the methodology fits the way you trade.